 |
|
||||||||
   |
||||||||

A Look Into the Markets |
Interest rates moved mostly sideways this week and finished off the worst levels, giving the market a slightly better tone heading into next week. There was plenty to digest, from stronger demand for Treasuries to the Fed Minutes and renewed pressure from overseas. Let’s recap what happened and look ahead to what could move rates next. "You just call on me brother, when you need a hand Treasury Auction gets an A+ The old saying is that the cure for higher rates is higher rates. When yields move high enough, bonds can start looking attractive again. That appeared to be the case this week as buyers stepped into the longer end of the Treasury market. We saw this in the 10-year Treasury note auction, where demand was solid. The takeaway is simple: strong demand for Treasuries can help stabilize the bond market. And a more stable bond market can help mortgage rates settle down. This does not mean rates are ready to drop sharply, but it does show that investors are becoming more interested at these higher yield levels. That helped rates move off the worst levels of the week. Fed Minutes Released The Fed Minutes showed officials remain focused on inflation, but the market still does not expect another rate hike at the October meeting. Current odds of an October hike remain low, near 20%. That tells us investors believe the Fed is more likely to wait and review the next round of inflation and economic data before making another move. For housing, this matters because mortgage rates are driven by expectations. If inflation cools, rates may find more stability. If inflation stays sticky, volatility can return quickly. French Connection Global rates also added pressure this week, especially from France, where borrowing costs have moved sharply higher. Why does that matter here? Bond markets are global. When rates rise in a major overseas market, it can push investors to demand higher yields elsewhere, including in the U.S. The encouraging part is that U.S. Treasuries still saw solid demand this week despite that global pressure. That helped keep rates from ending at the worst levels. 30-Year Mortgage Rates and 10-Year Note 30-Year Fixed Mortgage Rate (Freddie Mac daily average, October 8, 2026)
10-Year Treasury Note Yield (daily close, October 8, 2026)
Looking Ahead Next week brings a full calendar of reports that could influence the next move in rates. The biggest focus will be September CPI and PPI, which measure inflation at the consumer and wholesale levels. These reports are key because inflation remains the Fed’s biggest concern. We will also get September Retail Sales, which will show whether consumers are still spending despite higher borrowing costs. Strong spending could keep pressure on rates, while softer spending could help bonds. The October Philly Fed and Empire Index will give an early read on manufacturing activity, while September Existing Home Sales will provide an important update on the housing market. Weekly Jobless Claims will also be watched closely, as the labor market remains a major factor in Fed policy. Finally, the Fed’s quiet period for the October 27–28 FOMC meeting begins Saturday, October 17. Once that starts, Fed officials will stop giving public policy comments, meaning the data will do the talking. |
Mortgage Market Guide Candlestick Chart |
|
Each candle represents one day of trading. As mortgage bonds prices move higher, rates move lower. You can see on the right side of the chart, how mortgage bond prices are trading near 2026 price lows. Chart: Fannie Mae 30-Year 6.5% Coupon (Friday, October 9, 2026)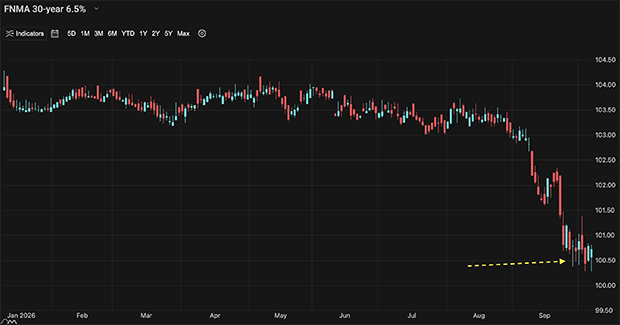 Economic Calendar for the Week of October 12 - 16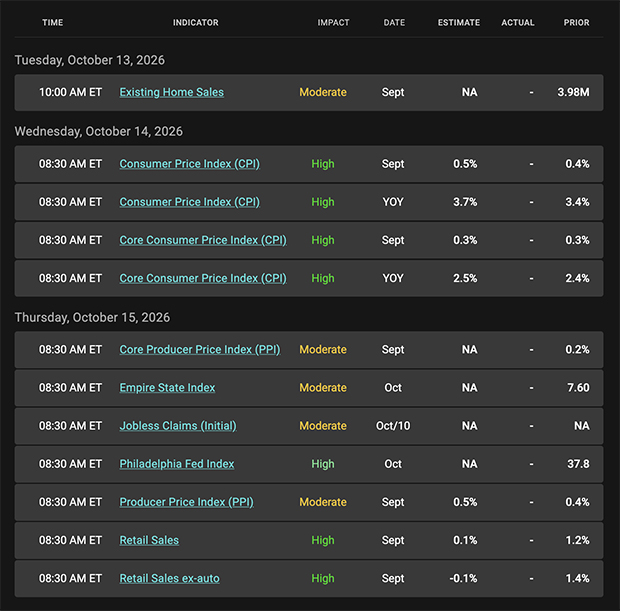 |